Put your own numbers into the free version below — no sign-up.
Your result shows up right here, as you type.
Want to keep it, print it or do it again next time? That is what the full version adds — see "What you get".
What you get: the same 12 formulas in an .xlsx plus a 10-quote comparison sheet (rate, points, lender fees) ranked by after-tax rate, and a dated sources sheet.
Most mortgage rate calculators assume your interest is deductible. In 2026 it only saves tax when your itemized deductions beat the $32,200 standard deduction (married filing jointly), and the restored PMI deduction is gone above $109,000 of AGI. See the rate you really pay, after tax, before you lock.
Comparing mortgage rates in 2026? Your interest only cuts your tax if your itemized deductions beat the $32,200 standard deduction (married filing jointly), mortgage insurance is deductible again but not above $109,000 of AGI, and the SALT cap is $40,400. Type your quote, income and taxes to see the rate you really pay after tax.
Your numbers
Your result
Mortgage interest for one year (balance × rate)
-
Interest deductible under the $750,000 debt limit
-
PMI cut: $1,000 steps of AGI over $100,000
-
Mortgage insurance you can deduct in 2026
-
Your 2026 SALT cap after the income phase-down
-
State and local taxes you can deduct
-
Itemized deductions with the mortgage
-
Deduction the mortgage adds over your best option
-
Federal tax the mortgage really saves in 2026
-
Your after-tax mortgage rate (interest + PMI)
-
Rule-of-thumb rate: rate × (1 − bracket)
-
Tax saving the rule of thumb overstates
-
Everything updates as you type. Nothing is uploaded. This runs in your browser.
Full version — $21 once (.xlsx that ranks up to 10 lender quotes with points and fees by after-tax cost, plus a dated sources sheet) Get it →
Get the full calculatorFull version: all tabs, your own file, works offline.
Sent. Check your inbox.
Enter your email above and we will unlock the download.
Sources: Rev. Proc. 2025-32 — 2026 standard deduction $32,200 married filing jointly, $24,150 head of household, $16,100 single. One Big Beautiful Bill Act (Public Law 119-21) — 2026 SALT cap $40,400, reduced by 30% of MAGI over $505,000, not below $10,000; $750,000 home acquisition debt limit made permanent; mortgage insurance premiums deductible again from 2026, cut 10% per $1,000 (or part) of AGI over $100,000. Federal only; not for married filing separately or pre-December 16, 2017 debt. Interest is balance × rate for one year. 2026 Schedule A is filed by April 15, 2027.
Example result
Get the full version $21
$21 once: the same 12 formulas in an .xlsx plus a 10-quote comparison sheet (rate, points, lender fees) ranked by after-tax rate, and a dated sources sheet.
One payment, one licence key for this tool. The key is shown right after payment.
Rev. Proc. 2025-32 (IRS, October 2025): 2026 standard deduction $32,200 married filing jointly, $24,150 head of household, $16,100 single. One Big Beautiful Bill Act (Public Law 119-21): SALT deduction cap $40,400 for 2026, reduce
Need more than this one? ReadyStack Pass opens all 679 files and 561 full versions — $29/month or $199/year. See the Pass →
Questions people ask
What does this mortgage rates calculator work out?
It turns one mortgage rate quote into the rate you really pay after federal tax in 2026. It applies the $750,000 debt limit, the restored PMI deduction and its phase-out above $100,000 of AGI, your 2026 SALT cap of up to $40,400, and compares your itemized total with the standard deduction to show the tax the mortgage actually saves.
Who is this calculator for?
US homebuyers and homeowners refinancing in 2026 who are comparing rate quotes, and the loan officers and tax preparers who help them. It matters most if you itemize close to the standard deduction, pay mortgage insurance, earn between $100,000 and $110,000, or have income above $505,000 where the SALT cap shrinks.
Why not use a free mortgage calculator or the usual rule of thumb?
Free mortgage calculators show the monthly payment and stop there. The rule of thumb, rate times one minus your bracket, assumes every dollar of interest is deductible. In 2026 only the part of your itemized deductions above the $32,200 joint standard deduction saves tax, and PMI stops being deductible above $109,000 of AGI.
What is free and what is in the paid file?
The full check for one quote is free in your browser with no limit: twelve results, from deductible interest to the after-tax rate and the overstated saving. The paid .xlsx adds a comparison sheet for up to 10 lender quotes with points and fees, ranked by after-tax cost, plus a dated sources sheet.
What does a wrong after-tax rate cost?
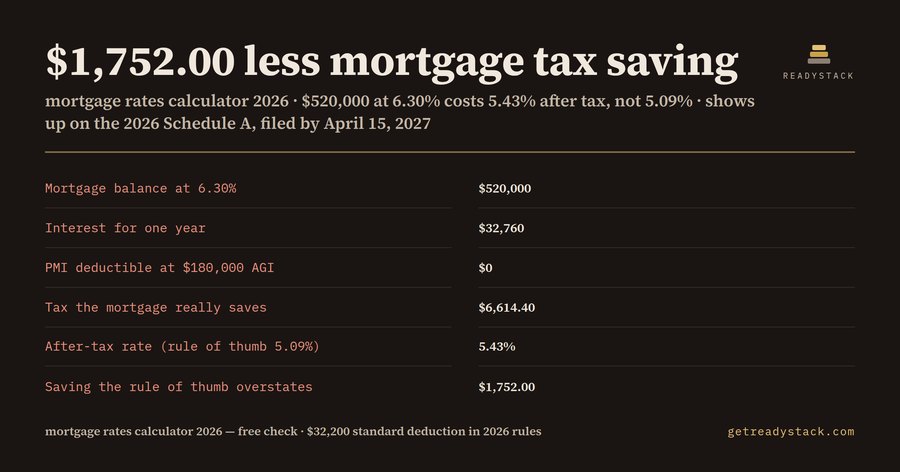
In the example, a $520,000 loan at 6.30% with $180,000 of income, the rule of thumb promises $8,366.40 of tax saving a year; the real figure is $6,614.40. That is $1,752.00 a year the budget counted on and never gets. The comparison file is a one-time $21 payment, not a subscription.
Ask about this tool
One question, answered by the person who built it. Your email only if you want the answer sent.
Embed this calculator on your site (free)
Paste this code into your page. It runs in your visitor’s browser and stays up to date. Nothing your visitors type is stored.
For businesses: your name and logo instead of ours, and each visitor’s result + e-mail in your inbox (only when they tick consent) — Pro from $19/month. See Pro →
Same job, next tool
Free in the browser. The full version is a one-time licence.
A copy of what you see above, in your inbox — the tool stays free, nothing here is locked.
For a team or company: for an invoice with your company details, a quote or several licences, write to support@getreadystack.com.
Who is behind this page
ReadyStack is a small team. We build each tool for one job people keep asking about, from the rules and sources named on the page, and we run it on the worked example you see here before it goes live.